Falling behind on the mortgage is more common than most people think, and you almost always have more time and more choices than the first letter makes it seem. Our free guide walks through all of them, keeping the house first, in plain words.
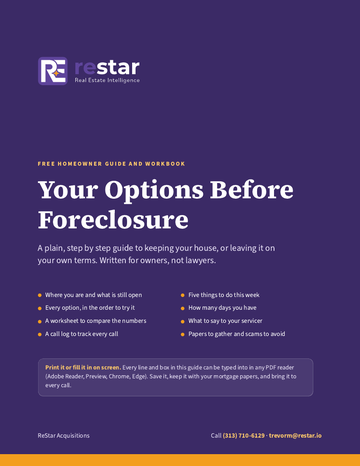
13 pages: checklists, a worksheet, a call script and an 11-call log. Print it or fill it in on screen. Free.
Educational only. This explains how these situations generally work. It is not legal, tax or financial advice, and the rules differ by state — talk to an attorney or CPA about your own situation before you act on any of it.
Options narrow as the process moves, so start by finding your stage. Timelines vary by state; your notices give your exact dates.
Every option is open. Late fees are the main cost so far.
Do now: Call the servicer and ask what it takes to catch up. If the problem is short term, ask about a repayment plan before a third payment is missed.
Still every option. Federal rules generally stop the first foreclosure filing until you are more than 120 days behind.
Do now: Send a complete loss mitigation application now. This is the window the 120 day rule exists for. Book a free housing counselor.
Most options are still open, but the clock is now set by your state, not by you.
Do now: Find the deadlines in the notice. Keep working the application. If selling may be the answer, get the house valued now; a listing needs 60 to 90 days.
Fewer options. A listing is hard under about six weeks. A cash sale, a short sale approval or an attorney may still stop the sale.
Do now: Call the servicer about postponing the sale, call an attorney if bankruptcy is on the table, and get any sale offers in writing with a closing date before the sale.
Federal rules generally stop a servicer from making the first foreclosure filing until a loan is more than 120 days behind, and that window exists so you can apply for help. If a complete application reaches the servicer more than 37 days before a scheduled sale, the servicer generally cannot hold the sale while it is being reviewed. Getting the application in early is the single most useful thing you can do.
Work down the list. Each one you rule out is still progress, because it tells you what the next call should be. The guide covers each one in more depth, including what it does to your credit and who to call.
| Option | What it is | Best when | Time it needs |
|---|---|---|---|
| Reinstatement | Pay everything past due, plus fees, in one payment. The loan carries on as before. | You can raise the money, from savings, family or a 401(k) hardship withdrawal. | Days |
| Repayment plan | Pay the normal payment plus part of the past due amount each month until caught up. | The hardship is over and your income can cover a bit more than the payment. | 2 to 4 weeks to set up |
| Forbearance | Payments are paused or reduced for a set time, then repaid later. | The hardship is temporary: a job gap, an illness, a disaster. | 1 to 3 weeks |
| Loan modification | The loan terms change (longer term, lower rate, missed payments added to the balance) so the payment fits your income. | Your income has dropped for good but can still cover a lower payment. | 30 to 90 days |
| Refinance or family help | A new loan or a family member pays off the old one. | You have equity and your credit still qualifies, or family can step in. | 30 to 45 days |
| Chapter 13 bankruptcy | A court plan to catch up over 3 to 5 years. Filing pauses a foreclosure sale. | You have steady income and other debts too. A last resort: compare Plan B first, because a sale can keep more of your equity and your credit. | Days to file |
| Option | What it is | Best when | Time it needs |
|---|---|---|---|
| List with an agent | Sell on the open market and keep what is left after the loan and costs. | You have equity, the house shows well, and you have 60 to 90 days before any sale. | 60 to 90 days |
| Sell as is for cash | A cash buyer takes the house in its current condition. No repairs, no showings. | Time is short, the house needs work, or you want a sure closing date. | 2 to 4 weeks |
| Short sale | The lender agrees to accept less than you owe when the house sells. | You owe more than the house is worth. | 60 to 120 days for lender approval |
| Deed in lieu | You hand the house to the lender instead of a foreclosure. Some lenders add moving money. | You owe more than it is worth and there is no second loan or lien. | 30 to 90 days |
Letting the house go to auction is the outcome every option above is trying to avoid. It usually brings the lowest price, the worst credit result and a move on someone else's date.
Thirteen pages you can print and fill in with a pen, or type into on screen and save. Every blank is a fillable field.
Get the free guide →Never pay an upfront fee to anyone who promises to stop a foreclosure, never stop talking to your servicer because someone told you to, and never sign your deed over to someone who says you can rent it back and buy it back later. See the CFPB's scam warnings. That includes us: we will never ask you for money.
Work every option first. If keeping the house is not going to work, or you want a sure date while the lender decides, a written cash offer lets you compare a sale with a listing, a short sale or the auction using real numbers.
Step 1 of 5
Send the address. We will send a written cash offer you can hold while you work on the loan. If another option beats ours, we will tell you.
You’ll talk to Trevor McAmis, Owner & Acquisitions Lead
(313) 710-6129
Takes about two minutes. Or call (313) 710-6129 — we answer.
We are a cash home buyer, not attorneys, lenders or housing counselors. This page and the guide are general information, not legal, tax or financial advice. Rules differ by state; for your own situation, talk with a HUD-approved counselor or an attorney.