Send the address and get a written cash offer within 24 hours. You pick the closing date. No repairs, no cleaning, no agent commissions.

Step 1 of 5
Start with the address. A few quick questions come next, then your written offer. There is no obligation.
You’ll talk to Trevor McAmis, Owner & Acquisitions Lead
(313) 710-6129
Takes about two minutes. Your address is never shared.
The address is enough to start in Milton. If you know the condition or the age of the roof, tell us. It helps us reach a firmer number sooner.
A real number on paper, with the recent sales nearby and the repair costs behind it. There is no obligation, and nothing to sign.
Seven days if you need it, ninety if you would rather take your time. We buy the house as it is, cover the standard closing costs, and you can leave behind what you do not want.
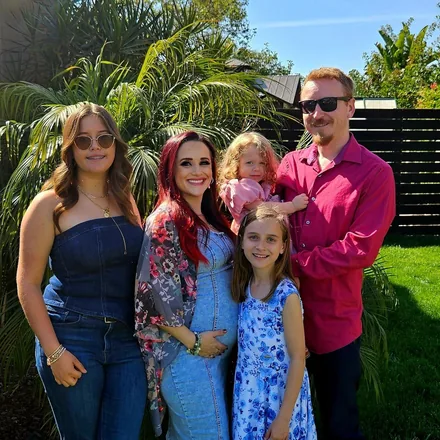
ReStar Acquisitions is run by Trevor McAmis and his family. Every offer on this site is underwritten by a person who will tell you when listing beats selling to us. Call (313) 710-6129 and you get one of us.
From our own transaction records and HUD data for Milton ZIP codes. Updated 2026-11-20.
Across the Milton properties in our records, the median time on market is 47 days. A cash sale skips that wait. There is no listing period, no showings, and no bank loan that can fall through at day 30.
The typical Milton home we look at was built in 1992. At that age, the roof, the original wiring and the heating and cooling are what most often end a retail contract after inspection. We buy the house as it is and price the repairs into the offer, so you do not have to make them.
Where there is an association we pull the estoppel early; unpaid dues and open violations settle at closing rather than blocking the sale.
In a steady market, the gap between an updated house and a dated one is wider than the gap between selling in spring and selling in fall.
That is 3 ZIP codes across Milton, including 32570, 32571, 32583. Not listed? We still look at it. Florida houses outside these ZIPs come to us regularly.
Figures for the whole market in every Milton ZIP code we buy in, from the ReStar housing database · August 2026. These are not our numbers. They cover every sale in the ZIP, not just ours.
Listings in Milton are moving faster than a year ago: a median of 62 days to go under contract, 9 days quicker. That is only the wait until it goes under contract. A buyer with a bank loan then needs another 30 to 45 days to close, if the loan holds. If the house is ready to list and there is no date you are working toward, listing it is a real option, and we will say so.
Median rent of $1,906 against a median sale price of $322,361 means a year of rent comes to about 7.1% of the price. That is the honest reason we can pay cash in Milton: many of these houses work as rentals for us, so we do not depend on reselling quickly.
| ZIP | Median sale | Per sq ft | Days on market | Listed now | Median rent |
|---|---|---|---|---|---|
| 32570 | $322,361 | $172 | 62 days | 136 | $1,679 |
| 32571 | $344,279 | $179 | 54 days | 227 | $1,946 |
| 32583 | $321,761 | $175 | 69 days | 210 | $1,906 |
Source: ReStar (restar.io) housing database, built from public records and MLS-derived feeds. A dash means that ZIP has no published figure for that measure this month.
Comparing a market with its county shows which buyers can afford it and how long they take to decide. Here is Santa Rosa County next to the Milton ZIP codes.
| Santa Rosa County | Milton ZIPs | |
|---|---|---|
| Median sale price | $349,119 | $322,361 |
| Price per sq ft | $192 | $175 |
| Days on market | 70 days | 62 days |
| Median rent | $1,975/mo | $1,906/mo |
| Median household income | $91,922 | — |
The Milton ZIP codes we buy in run 8% below the Santa Rosa County median of $349,119. That gap is why a countywide price per square foot will not price your house well, and it is why we work out our offers by ZIP.
Time on market differs too: a median of 62 days in the Milton ZIP codes against 70 days across Santa Rosa County.
County-wide, the median sale price is -3.6% against a year ago.
County figures from the ReStar housing database; the Milton column is the median across the ZIP codes listed above. Income is the most recent Census estimate.
Milton is a steady market, not a hot one. The median sale is around $322,000 in 32570 and 32583 and about $344,000 in 32571 on the Pace side, houses close at roughly 98.5% of list, and listings take a median of 54 to 69 days to go under contract (August 2026 figures). A clean house with a recent roof sells here without our help.
The houses that reach us are not that house. The typical one has three bedrooms, two baths and about 1,640 square feet, built in 1992, and more than half of our Milton files came from distress: a probate, a pre-foreclosure, a lis pendens already recorded. Florida forecloses through the courts, so a recorded lis pendens usually means months, not weeks, but the clock is running and the fees keep stacking on the payoff.
A 1992 house in Santa Rosa County runs into Florida insurance before it runs into a buyer. Carriers generally want a four-point inspection on homes this age (roof, electrical, plumbing, HVAC) and a wind mitigation report, and an older roof can make a house hard to insure at all. A financed buyer cannot close without a policy. A cash buyer can.
Milton is also home to NAS Whiting Field, so we see owners with orders and a fixed report date. If you need the sale to land on a specific day, tell us the day. Picking the closing date is part of the offer, not a favor.
We do not yet publish a median sale price for Milton, so this table uses rates, not dollars. We would rather show you a true percentage than a made-up price. Multiply by what your house is worth.
| Cost | Share of the sale price | Selling to us |
|---|---|---|
| Agent commission, both sides | about 5.5% | None |
| Documentary stamp tax, $0.70 per $100 of consideration | 0.7% | We pay it |
| Owner's title policy and settlement fees | roughly $1,500 to $2,500 | We cover the standard ones |
| Buyer concessions and post-inspection credits | about 1% | None. There is no inspection contingency |
| Repairs, cleaning and staging before listing | 1% and up | None. We buy the house as it is |
| Total cost to sell | about 8.2 to 10.2% of the sale price | $0 |
Net proceeds = sale price − mortgage payoff − closing costs − commissions − repairs and concessions
On a Florida listing, roughly 8.2 to 10.2 percent of the price is gone before any loan payoff comes out. A cash offer starts below retail but carries none of those five costs. That is why the two routes land closer together than the headline numbers suggest.
Customary rates, not a quote on your property. Commission is negotiable, and county and municipal add-ons vary within Florida. See the full cash offer versus listing comparison.
Florida closings usually run through a title company, and the two things that hold them up here are insurance and permits. An open or unpermitted improvement has to be resolved or explicitly accepted, and wind mitigation drives what a financed buyer can afford to insure. Cash removes the insurance dependency entirely.
On our side the steps are the same every time: a title search, payoff figures ordered on any existing mortgage, liens and municipal balances found, then the money sent and the deed recorded. A cash sale does not skip title work. What it skips is the lender, the appraisal and the financing contingency, which is where most retail contracts on Milton houses fall apart.
General information about how these transactions typically proceed, not legal or tax advice. Your closing agent or attorney is the authority on your specific file.
Every row below comes from a statute, not our opinion, and each one links to the source so you can check it yourself. These are also the items that most often hold up a closing in Milton.
| Seller disclosure required | Fla. Stat. § 689.302: read the statute |
| Transfer or excise tax | Documentary stamp tax, $0.70 per $100 of consideration |
| Rate used in the costs below | 0.7% |
| Who pays it | Seller |
| Statutory authority | Fla. Stat. § 201.02: source |
| Who conducts the closing | title company |
| Attorney required at closing | No |
Florida has no general statutory disclosure form, but under the Johnson v. Davis rule a seller must disclose known material defects that are not readily observable. Since 1 October 2024 a written flood disclosure is required by statute at or before you sign the contract.
Miami-Dade charges $0.60 per $100 plus a surtax on anything other than a single-family home; the rest of the state is $0.70.
Florida closings are conducted by a title company, or by a real estate attorney if you prefer one. Neither is required by statute; the title agent is the norm.
Florida has no state income tax, so only federal capital gains rules apply. Federally, the exclusion for a primary residence shelters up to $250,000 of gain if you are single and $500,000 if you are married filing jointly, provided you owned and lived in the house for two of the last five years. See IRS Topic 701. An inherited property takes a stepped-up basis at the date of death, which usually means little or no taxable gain if you sell soon after.
General information about Florida practice, current as of 2026-11-20. It is not legal or tax advice, and rates set at county or municipal level vary within the state. Your closing agent, attorney or CPA is the authority on your file.
| Listing with an agent | Our cash offer | |
|---|---|---|
| Agent commission | About 6% of the sale price | None |
| Repairs before closing | Buyer and appraiser both have a say | None. We buy the house as it is |
| Cleaning and showings | Open houses and strangers walking through | Neither |
| Time to close | 47 days on the market, then another 30 to 45 days to close | 7 to 14 days once title is clear |
| Financing falls through | A common reason a sale falls apart | No lender involved |
| Closing costs | Usually paid by the seller | We cover the standard ones |
| Certainty of the number | The buyer can ask for a lower price after inspection | The written number is the number |
The listing timeline is the median days on market for Milton in our own records, plus a typical closing with a bank loan. Commission is the customary 6% and varies by agreement.
If you accept an offer, you have three days after signing to walk away for any reason at all. You owe nothing, and you do not have to explain. We would rather not buy the house than have you feel pushed into selling it.
If the house is in good shape and you are not in a hurry, listing it will almost always net you more than we can offer. We are not being modest. Our offer is lower than a retail sale because we take on the repairs, the carrying costs and the risk.
If that sounds like your house, we will tell you so. It saves time for both of us, and it beats pretending otherwise.
Every house comes with its own story and its own timing. These pages explain what changes in each case:
You can usually still sell the house before that date.
We can buy while the estate is being settled, and wait for the paperwork.
One clear closing date, and the proceeds split cleanly.
Occupied is fine. You do not have to remove anyone first.
These get paid out of the proceeds at closing.
Fire, water or structural damage. We price it in, and you do not repair it.
We buy across Florida, not just Milton. Each of these has its own sale prices, ZIP breakdown and rent data published the same way:
Yes. The payoff comes out of the proceeds at closing. The only case that gets difficult is owing more than the house is worth, and we will tell you that right away.
Typically 7 to 14 days once title is clear, because there is no bank loan to wait on. For comparison, the median Milton listing in our records sits 47 days before it is even under contract, and closing takes another 30 to 45 days after that.
Possibly, and we will say so. If it is sound, clean, and you can wait 60 to 90 days and pay commissions, the open market usually leaves you with more. We make more sense when it needs work you would rather not pay for, or you need a date you can count on.
Documentary stamp tax, $0.70 per $100 of consideration, about 0.7% of the price. Seller pays it under Fla. Stat. § 201.02. Miami-Dade charges $0.60 per $100 plus a surtax on anything other than a single-family home; the rest of the state is $0.70. On a cash sale to us it comes out of our side of the settlement statement, not yours.
No. Florida closings are conducted by a title company, or by a real estate attorney if you prefer one. Neither is required by statute; the title agent is the norm.
Florida has no general statutory disclosure form, but under the Johnson v. Davis rule a seller must disclose known material defects that are not readily observable. Since 1 October 2024 a written flood disclosure is required by statute at or before you sign the contract. The citation is Fla. Stat. § 689.302. Selling the house as it is does not remove the obligation. It changes who pays for the repair, not whether you have to mention it.
Between about 8.2% and 10.2% of the sale price on the listing route: roughly 5.5% in agent commission, 0.7% in transfer tax, $1,500 to $2,500 in title and settlement fees, about 1% in buyer concessions and 1% or more in repairs before listing. A cash sale to us carries none of it.
There is no fixed percentage, and any buyer quoting one before seeing the house is guessing. The offer is what the house would sell for once repaired, minus repairs, minus holding and resale costs, minus the buyer's margin. Repairs are the line that moves most: a house needing only paint and finishes lands far higher than one needing a roof, heating, plumbing or wiring. Ask any buyer to walk you through all four lines on your house.
Sometimes, through a short sale, but that needs your lender's written approval and takes months, not days. If that is where things stand, we will tell you on the first call rather than let you find out two weeks in.
Yes. We buy in any condition. There are no repairs, no cleaning and no staging, and you can leave behind anything you do not want. Selling as it is changes who pays for the work, not what you have to disclose about it.
It means the purchase is paid for without a mortgage, so there is no lender, no appraisal and no financing contingency. That is the whole advantage: a buyer's loan falling through is a common reason a home sale falls apart, and it cannot happen on a cash purchase.
Check it against the recorded sales published on this page and the four lines of math above it. We show you the recent sales nearby that the number came from. If listing would leave you with more, we will say so. That conversation is quicker for both of us than the alternative.
None. There is no agent commission and no listing fee, and we cover standard closing costs. The number on the offer is what you receive, less anything still owed on a mortgage or lien.
No. The offer is written, free, and yours to walk away from. We would rather you compare it with a listing than feel pushed into it.
Send the address. Within a day you get a written offer, with the recent sales nearby behind it. If listing would leave you with more, we will tell you that instead.
Also see other Florida markets we buy in, how the offer is calculated, and the situations we help with.
Step 1 of 5
A few quick questions come next, then your written offer. There is no obligation.
You’ll talk to Trevor McAmis, Owner & Acquisitions Lead
(313) 710-6129
Takes about two minutes. Your address is never shared.
