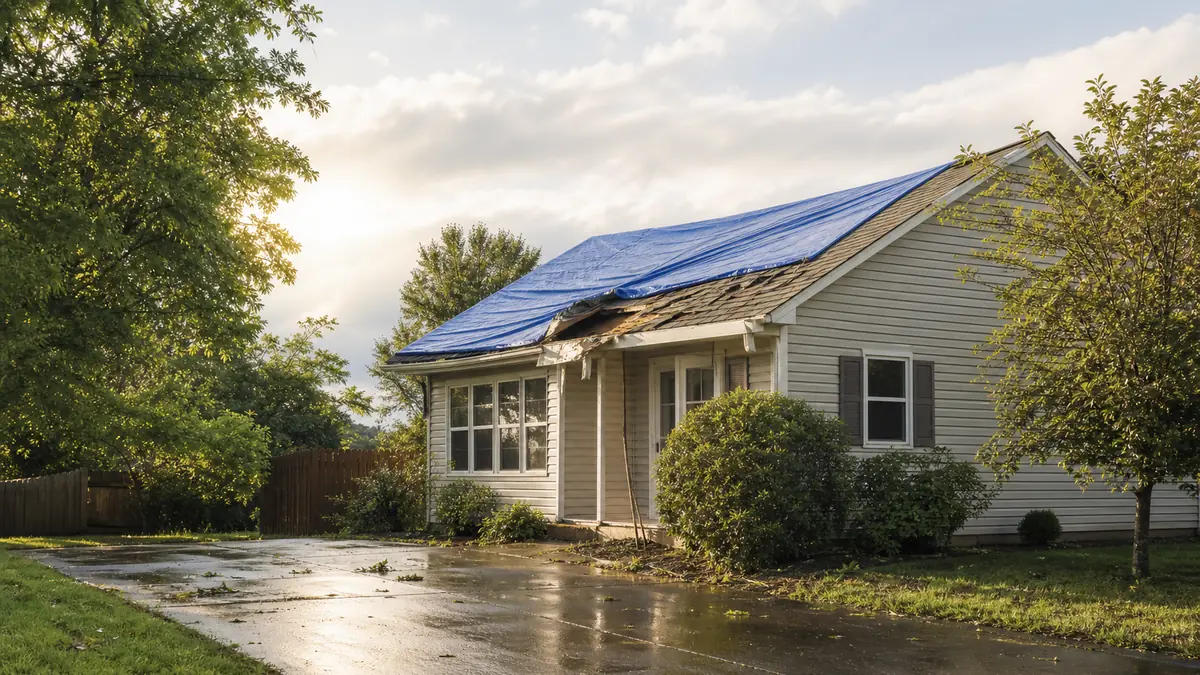
Damage that an insurer will not fully cover
Fire, water, storm and structural damage share a pattern: the claim covers part of it, the estimate for the rest is more than the house is worth to you, and meanwhile it is not habitable and you are still carrying it. We buy in that state. You do not need to complete repairs, get competing contractor bids, or settle the claim before selling.
Insurance proceeds are a negotiable part of the deal
If you have already received a payout, or expect one, that is a term we work out in the offer — sometimes you keep it and the price reflects that, sometimes it is assigned with the sale. Either way it should be an explicit line in the conversation, not a surprise at closing. Tell us where the claim stands when you first write.
Vacant and unsecured is a clock
A damaged, empty house tends to get worse: a vacancy exclusion can void coverage, one heating season can burst supply lines, and copper theft is real. The value we can offer generally goes down the longer it sits, which is the honest reason not to wait on this one.
What to have ready
- What caused the damage and roughly when
- Whether a claim was filed, and its status
- Any contractor estimates you have
- Whether the property is currently occupied
We are a cash buyer, not attorneys or accountants. Nothing here is legal or
tax advice — for a foreclosure, probate or divorce matter, talk to your attorney too.
Questions people ask about this
- Will you buy a fire-damaged house?
- Yes, including structural fire damage. We assess what it takes to bring it back and price from there. You do not need to demolish, clean, or make it safe first.
- Should I settle my insurance claim first?
- Not necessarily. Sometimes it is cleaner to settle first and sometimes it is better handled as part of the sale. Tell us where the claim stands and we will lay out both.
- Is mold a dealbreaker?
- No. Mold, water damage and the remediation that follows are routine for us and are exactly what stops a mortgage buyer.
Who you will be dealing with
Trevor McAmis
Owner & Acquisitions Lead, Restar Acquisitions. (313) 710-6129 · More about us
Every offer on this site is underwritten by a person, not a form. If the
numbers do not work for you, say so and I will tell you what would.
The rest of the process is the same either way
The three steps, the cash-offer versus listing comparison, the three-day right to cancel and
the four-line math behind the number live on
how it works rather than being repeated here. This page is
only what changes when major damage a lender will not finance.
Next
Other situations we handle, or
your local market — every market page publishes its own
sale prices, ZIP breakdown and rent data.