Send the address and get a written cash offer within 24 hours. You pick the closing date. No repairs, no cleaning, no agent commissions.
Step 1 of 5
Start with the address. A few quick questions come next, then your written offer. There is no obligation.
You’ll talk to Trevor McAmis, Owner & Acquisitions Lead
(313) 710-6129
Takes about two minutes. Or call (313) 710-6129 — we answer.
The address is enough to start in Baltimore. If you know the condition or the age of the roof, tell us. It helps us reach a firmer number sooner.
A real number on paper, with the recent sales nearby and the repair costs behind it. There is no obligation, and nothing to sign.
Seven days if you need it, ninety if you would rather take your time. We buy the house as it is, cover the standard closing costs, and you can leave behind what you do not want.
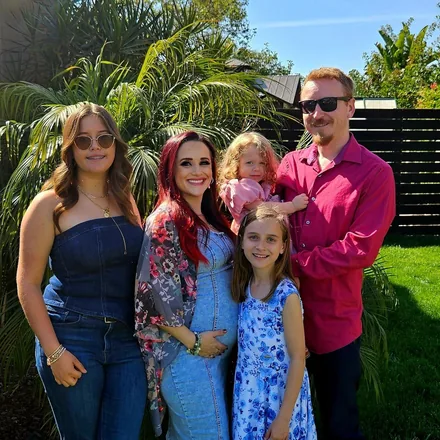
ReStar Acquisitions is run by Trevor McAmis and his family. Every offer on this site is underwritten by a person who will tell you when listing beats selling to us. Call (313) 710-6129 and you get one of us.
From our own transaction records and HUD data for Baltimore ZIP codes. Updated 2026-10-29.
The typical Baltimore home we look at was built in 1920. At that age, the roof, the original wiring and the heating and cooling are what most often end a retail contract after inspection. We buy the house as it is and price the repairs into the offer, so you do not have to make them.
Baltimore rowhouses bring two things almost nowhere else does: ground rent that must be identified and redeemed before title will clear, and a shared party wall with whatever is happening next door. Both are routine for us and disqualifying for most mortgage buyers.
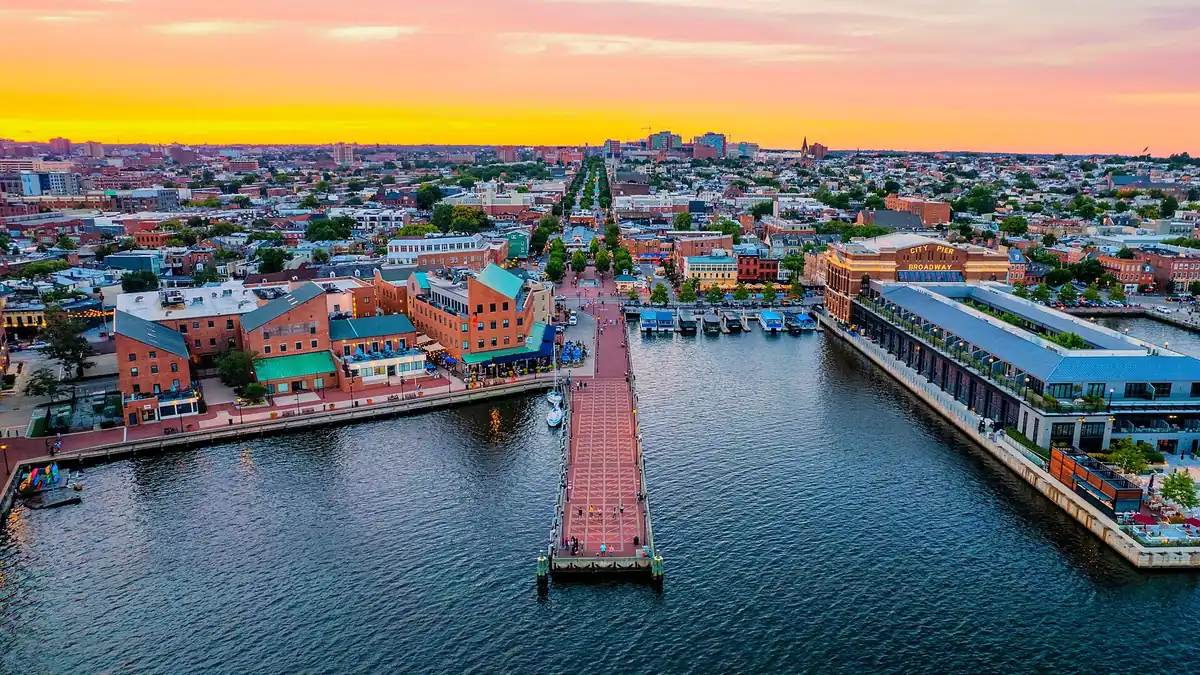
City-level numbers say very little here. We underwrite the block, not the ZIP.
Ground rent still exists on many parcels here and must be identified and redeemed or assumed before title will clear. It is routine for us and a common reason mortgage buyers fall out.
That is 18 ZIP codes across Baltimore, including 21202, 21205, 21206 and 21207. Not listed? We still look at it. Maryland houses outside these ZIPs come to us regularly.
Figures for the whole market in every Baltimore ZIP code we buy in, from the ReStar housing database · August 2026. These are not our numbers. They cover every sale in the ZIP, not just ours.
The median Baltimore listing takes 42 days to go under contract. That is only the wait until it goes under contract. A buyer with a bank loan then needs another 30 to 45 days to close, if the loan holds.
Home values across these ZIP codes are 1.5% lower than a year ago. On a vacant or inherited house, that is a second cost running alongside taxes, insurance and utilities while you decide.
There are +15.3% more homes on the market than a year ago, so a listing competes with more of them.
Median rent of $1,601 against a median sale price of $270,508 means a year of rent comes to about 7.1% of the price. That is the honest reason we can pay cash in Baltimore: many of these houses work as rentals for us, so we do not depend on reselling quickly.
| ZIP | Median sale | Per sq ft | Days on market | Listed now | Median rent |
|---|---|---|---|---|---|
| 21202 | $279,879 | $203 | 75 days | 105 | $1,711 |
| 21205 | $108,073 | $131 | 70 days | 96 | $1,857 |
| 21206 | $261,137 | $166 | 43 days | 110 | $1,607 |
| 21207 | $332,356 | $187 | 37 days | 90 | $1,439 |
| 21209 | $459,801 | $215 | 29 days | 57 | $1,754 |
| 21210 | $689,702 | $256 | 41 days | 29 | $1,750 |
| 21212 | $436,811 | $254 | 33 days | 90 | $1,686 |
| 21213 | $125,946 | $114 | 54 days | 209 | $1,740 |
| 21216 | $157,107 | $112 | 67 days | 182 | $1,547 |
| 21217 | $117,449 | $92 | 64 days | 201 | $1,529 |
| 21218 | $242,395 | $161 | 42 days | 220 | $1,454 |
| 21221 | $284,877 | $187 | 34 days | 93 | $1,685 |
| 21222 | $238,497 | $179 | 23 days | 129 | $1,391 |
| 21223 | $53,977 | $58 | 49 days | 297 | $1,596 |
| 21225 | $299,870 | $187 | 39 days | 96 | $1,416 |
| 21227 | $327,358 | $209 | 22 days | 70 | $1,487 |
| 21229 | $210,909 | $147 | 47 days | 153 | $1,528 |
| 21236 | $349,849 | $208 | 24 days | 75 | $1,768 |
Source: ReStar (restar.io) housing database, built from public records and MLS-derived feeds. A dash means that ZIP has no published figure for that measure this month.
Comparing a market with its county shows which buyers can afford it and how long they take to decide. Here is Baltimore city next to the Baltimore ZIP codes.
| Baltimore city | Baltimore ZIPs | |
|---|---|---|
| Median sale price | $224,498 | $270,508 |
| Price per sq ft | $158 | $183 |
| Days on market | 49 days | 42 days |
| Median rent | $1,764/mo | $1,601/mo |
| Median household income | $62,177 | — |
The Baltimore ZIP codes we buy in run +20% above the Baltimore city median of $224,498. That gap is why a countywide price per square foot will not price your house well, and it is why we work out our offers by ZIP.
Time on market differs too: a median of 42 days in the Baltimore ZIP codes against 49 days across Baltimore city.
County-wide, the median sale price is -0.2% against a year ago.
Note that Baltimore spans more than one county. 11 of the ZIP codes we buy in sit in Baltimore city and the rest fall outside it, so treat the county column as background, not as a guide to your house's price.
County figures from the ReStar housing database; the Baltimore column is the median across the ZIP codes listed above. Income is the most recent Census estimate.
We do not yet publish a median sale price for Baltimore, so this table uses rates, not dollars. We would rather show you a true percentage than a made-up price. Multiply by what your house is worth.
| Cost | Share of the sale price | Selling to us |
|---|---|---|
| Agent commission, both sides | about 5.5% | None |
| Baltimore City: 0.5% state + 1.5% city transfer + 1% recordation, about 3% combined | 1.5% | We pay it |
| Owner's title policy and settlement fees | roughly $1,500 to $2,500 | We cover the standard ones |
| Buyer concessions and post-inspection credits | about 1% | None. There is no inspection contingency |
| Repairs, cleaning and staging before listing | 1% and up | None. We buy the house as it is |
| Total cost to sell | about 9.0 to 11.0% of the sale price | $0 |
Net proceeds = sale price − mortgage payoff − closing costs − commissions − repairs and concessions
On a Maryland listing, roughly 9.0 to 11.0 percent of the price is gone before any loan payoff comes out. A cash offer starts below retail but carries none of those five costs. That is why the two routes land closer together than the headline numbers suggest.
Customary rates, not a quote on your property. Commission is negotiable, and county and municipal add-ons vary within Maryland. See the full cash offer versus listing comparison.
Maryland closings involve a title company or attorney, and ground rent is the item that most often surprises people. It must be identified and either redeemed or assumed before title will clear. Municipal water balances attach to the property too.
On our side the steps are the same every time: a title search, payoff figures ordered on any existing mortgage, liens and municipal balances found, then the money sent and the deed recorded. A cash sale does not skip title work. What it skips is the lender, the appraisal and the financing contingency, which is where most retail contracts on Baltimore houses fall apart.
General information about how these transactions typically proceed, not legal or tax advice. Your closing agent or attorney is the authority on your specific file.
Every row below comes from a statute, not our opinion, and each one links to the source so you can check it yourself. These are also the items that most often hold up a closing in Baltimore.
| Seller disclosure required | Md. Real Prop. § 10-702: read the statute |
| Transfer or excise tax | Baltimore City: 0.5% state + 1.5% city transfer + 1% recordation, about 3% combined |
| Rate used in the costs below | 1.5% |
| Who pays it | Split 50/50 by custom |
| Statutory authority | Md. Tax-Prop. § 13-203; Balt. City Code art. 28, subt. 17: source |
| Who conducts the closing | title company / settlement attorney |
| Attorney required at closing | No |
Maryland gives you a choice: complete a Residential Property Disclosure describing the condition of the property, or deliver a Disclaimer selling strictly as-is. Either way, latent defects you actually know about must still be disclosed.
Maryland custom is a 50/50 split between buyer and seller, so the figure used here is the seller's half of the combined Baltimore City burden. It is fully negotiable in the contract, and every other Maryland county sets its own rate.
Maryland settlements are conducted by a title company or a settlement attorney. Two Maryland-specific items decide the timeline here: ground rent, which must be identified and either redeemed or assumed before title clears, and the 8% non-resident withholding on net proceeds if you no longer live in the state.
Maryland income tax applies to gain above the federal exclusion, and non-residents have 8% of net proceeds withheld at settlement under Md. Tax-Gen. § 10-912. Federally, the exclusion for a primary residence shelters up to $250,000 of gain if you are single and $500,000 if you are married filing jointly, provided you owned and lived in the house for two of the last five years. See IRS Topic 701. An inherited property takes a stepped-up basis at the date of death, which usually means little or no taxable gain if you sell soon after.
General information about Maryland practice, current as of 2026-10-29. It is not legal or tax advice, and rates set at county or municipal level vary within the state. Your closing agent, attorney or CPA is the authority on your file.
| Listing with an agent | Our cash offer | |
|---|---|---|
| Agent commission | About 6% of the sale price | None |
| Repairs before closing | Buyer and appraiser both have a say | None. We buy the house as it is |
| Cleaning and showings | Open houses and strangers walking through | Neither |
| Time to close | 60 to 90 days, then another 30 to 45 days to close | 7 to 14 days once title is clear |
| Financing falls through | A common reason a sale falls apart | No lender involved |
| Closing costs | Usually paid by the seller | We cover the standard ones |
| Certainty of the number | The buyer can ask for a lower price after inspection | The written number is the number |
Listing timelines are typical, not measured. Commission is the customary 6% and varies by agreement.
If you accept an offer, you have three days after signing to walk away for any reason at all. You owe nothing, and you do not have to explain. We would rather not buy the house than have you feel pushed into selling it.
If the house is in good shape and you are not in a hurry, listing it will almost always net you more than we can offer. We are not being modest. Our offer is lower than a retail sale because we take on the repairs, the carrying costs and the risk.
If that sounds like your house, we will tell you so. It saves time for both of us, and it beats pretending otherwise.
Every house comes with its own story and its own timing. These pages explain what changes in each case:
You can usually still sell the house before that date.
We can buy while the estate is being settled, and wait for the paperwork.
One clear closing date, and the proceeds split cleanly.
Occupied is fine. You do not have to remove anyone first.
These get paid out of the proceeds at closing.
Fire, water or structural damage. We price it in, and you do not repair it.
They are paid from the proceeds at closing. Municipal water liens attach to the property, not to you personally, which is why they must be cleared as part of the sale.
Yes. Ground rent has to be identified and either redeemed or assumed for title to clear. It is routine here and it is one of the main reasons mortgage buyers fall out.
Baltimore City: 0.5% state + 1.5% city transfer + 1% recordation, about 3% combined, about 1.5% of the price. Split 50/50 by custom pays it under Md. Tax-Prop. § 13-203; Balt. City Code art. 28, subt. 17. Maryland custom is a 50/50 split between buyer and seller, so the figure used here is the seller's half of the combined Baltimore City burden. It is fully negotiable in the contract, and every other Maryland county sets its own rate. On a cash sale to us it comes out of our side of the settlement statement, not yours.
No. Maryland settlements are conducted by a title company or a settlement attorney. Two Maryland-specific items decide the timeline here: ground rent, which must be identified and either redeemed or assumed before title clears, and the 8% non-resident withholding on net proceeds if you no longer live in the state.
Maryland gives you a choice: complete a Residential Property Disclosure describing the condition of the property, or deliver a Disclaimer selling strictly as-is. Either way, latent defects you actually know about must still be disclosed. The citation is Md. Real Prop. § 10-702. Selling the house as it is does not remove the obligation. It changes who pays for the repair, not whether you have to mention it.
Between about 9.0% and 11.0% of the sale price on the listing route: roughly 5.5% in agent commission, 1.5% in transfer tax, $1,500 to $2,500 in title and settlement fees, about 1% in buyer concessions and 1% or more in repairs before listing. A cash sale to us carries none of it.
There is no fixed percentage, and any buyer quoting one before seeing the house is guessing. The offer is what the house would sell for once repaired, minus repairs, minus holding and resale costs, minus the buyer's margin. Repairs are the line that moves most: a house needing only paint and finishes lands far higher than one needing a roof, heating, plumbing or wiring. Ask any buyer to walk you through all four lines on your house.
Sometimes, through a short sale, but that needs your lender's written approval and takes months, not days. If that is where things stand, we will tell you on the first call rather than let you find out two weeks in.
Yes. We buy in any condition. There are no repairs, no cleaning and no staging, and you can leave behind anything you do not want. Selling as it is changes who pays for the work, not what you have to disclose about it.
It means the purchase is paid for without a mortgage, so there is no lender, no appraisal and no financing contingency. That is the whole advantage: a buyer's loan falling through is a common reason a home sale falls apart, and it cannot happen on a cash purchase.
Check it against the recorded sales published on this page and the four lines of math above it. We show you the recent sales nearby that the number came from. If listing would leave you with more, we will say so. That conversation is quicker for both of us than the alternative.
None. There is no agent commission and no listing fee, and we cover standard closing costs. The number on the offer is what you receive, less anything still owed on a mortgage or lien.
No. The offer is written, free, and yours to walk away from. We would rather you compare it with a listing than feel pushed into it.
Send the address. Within a day you get a written offer, with the recent sales nearby behind it. If listing would leave you with more, we will tell you that instead.
Also see other Maryland markets we buy in, how the offer is calculated, and the situations we help with.
Step 1 of 5
A few quick questions come next, then your written offer. There is no obligation.
You’ll talk to Trevor McAmis, Owner & Acquisitions Lead
(313) 710-6129
Takes about two minutes. Or call (313) 710-6129 — we answer.